Excel consulting for Harrisonburg businessesCall 949-464-7489

Harrisonburg, Virginia · Independent city

Excel Consulting Services in Harrisonburg, VA

Ask what a unit costs to make and the honest answer is a question back: how many did you make? Fixed cost spread over a long run and over a short one gives two very different figures, and the one on the price list was calculated at a volume you may no longer be running. JAAD Group provides Excel consulting in Harrisonburg for businesses that count their output in units.

  • Unit cost by volume
  • Batch size and changeover
  • Fixed-cost absorption
  • Automation and VBA
25+Years building Excel and Office systems for businesses
40+Person-hours a month returned on one reporting rebuild
1700Faster record retrieval after a workbook was restructured
66Improvement in budgeting accuracy across thirty entities

It depends how many

Unit Cost Is Not a Property of the Unit

A unit cost feels like a fact about the product and it is nothing of the kind. It is a fact about the product and the volume together: the same item costs materially more per unit at half the output, because the fixed cost it has to absorb has not changed and there are fewer units to carry it.

Which means every price list carries an assumption about volume inside it, usually unstated and frequently years old. When actual output drops below that assumption, margin erodes without any single decision having caused it.

Underneath sits a second effect most reporting misses entirely: changeover. Time spent switching from one product to another is capacity consumed producing nothing, and shorter runs mean proportionally more of it.

Both are calculable from records the business already keeps. What they produce is a unit cost expressed as a curve against volume rather than a single number, which is the only form that survives contact with a real production month.

Every price list has a volume assumption inside it. When output drops below that assumption, margin erodes with nobody having decided anything.

What the work is really about

What Excel Consulting in Harrisonburg Usually Involves

Separate variable cost from the fixed cost being absorbed

The first task is to split the cost of production into what genuinely varies per unit and what is simply being absorbed. Material, direct labor at the machine, consumables and energy while running move with volume. Supervision, rent, rates, insurance, maintenance contracts, certification and the depreciation charge do not move at all within a wide band, and they are being divided by however many units came out. Most businesses carry one blended unit cost that mixes the two and therefore cannot explain its own variability. Separating them takes a day with the cost ledger and the production records, and it is where Excel consulting on a production business starts.

Unit cost belongs on a curve, not in a cell

Second, once split, unit cost should be expressed as a curve across a range of volumes rather than as a single figure. The variable element is flat per unit; the fixed element falls as output rises; the sum is a descending curve that flattens out. Published at three or four volume points — the low month, the typical month, a full month — it immediately shows how sensitive the business is to output, and that sensitivity is the real risk being carried. A business whose cost barely moves across the range is robust. One whose cost swings widely is running a volume bet nobody named as such.

Changeover is capacity, and it has a price

Third, changeover deserves its own line because it is capacity rather than overhead. Setting up, cleaning down, running trial pieces and re-checking tolerances all consume productive time and produce nothing sellable, so the cost is the lost output rather than the labor involved. Measured per changeover and multiplied by frequency, it usually comes to a number that surprises people. It also explains a common complaint — the month where everything was busy and little was produced — which is nearly always a month with too many short runs.

Batch size is a calculation with an answer

Fourth, with changeover priced, economic batch size stops being a matter of opinion. Bigger batches spread the changeover over more units and raise the stock being held and financed; smaller batches cut the stock and multiply the changeovers. There is a size that minimizes the sum of those two costs, it is different for every product, and it is arithmetic rather than judgment once both inputs exist. Several businesses find their habitual run length is well away from it in one direction or the other. Working that out is a contained piece of financial modeling.

Under-absorption has to be visible in the month it happens

Fifth, under-absorption has to show up in the month it occurs rather than in a year-end adjustment. If output fell short of the volume the costing assumed, the shortfall is a real amount of fixed cost that no unit carried, and it is the single clearest explanation for a month that looked fine operationally and poor financially. Reported as its own line — expected absorption, actual absorption, the gap — it turns an unexplained variance into a known quantity with an obvious cause. That is routine Excel reporting and it is usually the first thing managers ask to see again.

This is structural rather than a purchase

None of this needs a manufacturing system. The production records, the cost ledger and the timesheets hold what is required; what is missing is the variable-fixed split, a cost curve and changeover priced as lost output. A short session with the production records open normally settles what is achievable, documented afterward — which is what Excel expert help covers.

What gets built

Excel Consulting Services in Harrisonburg, VA — The Six Areas

Six kinds of work. For a business counting units, the first and third carry most of the value.
Excel consultant splitting production cost into variable and absorbed fixed cost Structure

Variable Cost Against Absorbed Cost

Material and machine labor move with volume. Supervision, rent and certification do not. One blended unit cost mixes them and cannot explain its own variability.

  • Variable and fixed separated in the cost of production
  • Unit cost as a curve across three or four volume points
  • Formula repair for references that stopped pointing anywhere
  • Performance — volatile formulas replaced with tables and pivots

Related: Excel consulting
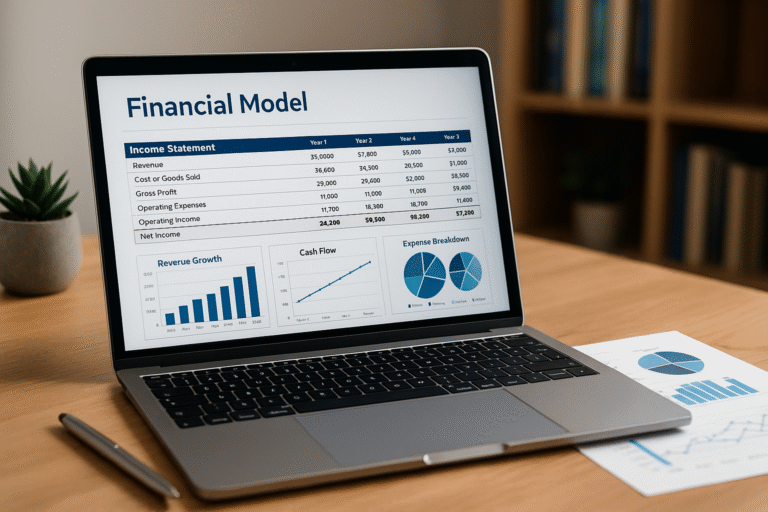
Excel model calculating economic batch size from changeover and holding cost Modeling

Economic Batch Size, Per Product

Bigger batches spread changeover and raise financed stock. Smaller batches do the reverse. There is a size that minimizes the sum, and it is arithmetic once both inputs exist.

  • Batch size derived product by product
  • Changeover against holding cost balanced explicitly
  • Scenario switching across demand and run-length changes
  • Assumptions in one visible block, never inside formulas

Related: Excel financial modeling
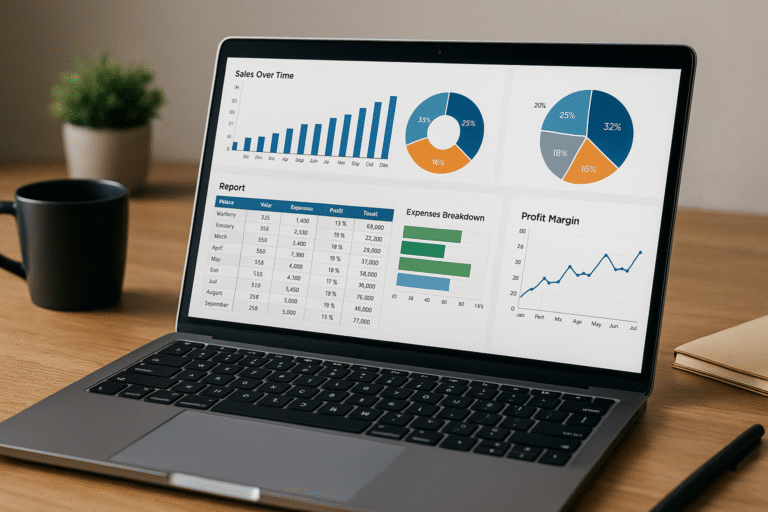
Excel report showing expected absorption, actual absorption and the gap Reporting

Under-Absorption, in the Month It Happens

Expected absorption, actual absorption, the gap. The clearest explanation there is for a month that looked fine on the floor and poor in the accounts.

  • Absorption gap reported monthly, not at year end
  • Changeover hours shown as capacity consumed
  • Live connections to the systems already holding the data
  • Exception flags when output falls under the costing volume

Related: Excel reporting

Automated consolidation of production, labor and cost records in Excel Automation

The Production Close Runs Itself

Output, labor and cost come from three places and the close currently waits on somebody joining them. Scheduled, the absorption report is ready at period end.

  • Scheduled consolidation across output, labor and cost
  • Refresh from source rather than from a saved download
  • Import cleanup for exports that shift format between runs
  • Volume trend against the costing assumption each period

Related: Excel automation
VBA routine capturing changeover start and finish against each production run Code

VBA So Changeover Gets Recorded

Changeover cannot be priced if nobody logs it. Entry that brackets each run with setup and cleardown times and refuses a run with neither.

  • Setup and cleardown logged around every run
  • Run cannot close without its changeover recorded
  • Deterministic routines for anything run every period
  • Legacy macro repair where whoever wrote it has gone

Related: VBA and macro development
Remote Excel expert help session with a Harrisonburg business Support

Expert Help and Team Training

Sometimes there is no project, only a quote going out on Friday and no confidence in the unit cost behind it. A short session usually produces a defensible figure.

  • Same-week attention when a quote will not wait
  • Training on your own files rather than on sample data
  • Written handover so the curve keeps being refreshed
  • Retained hours where there is no in-house Excel depth

Related: Excel expert help and MS Office training

Where it starts

Eight Conversations That Begin a Harrisonburg Excel Project

Openings we hear from businesses counting units, and what the answer usually turns out to be.

"What does a unit actually cost us?"

It depends how many you make, which is why the answer belongs on a curve rather than in a cell. The variable part is flat; the absorbed part is not.

"Margin fell and the price did not change."

Then volume probably did. Every price list has a volume assumption inside it, and output below that assumption erodes margin quietly.

"Busy month, not much produced."

Almost always too many short runs. Changeover is capacity consumed producing nothing, and shorter runs mean proportionally more of it.

"How long should a run be?"

A calculation once changeover and holding cost both exist. Habitual run lengths are frequently well away from the economic size.

"The accounts look worse than the floor felt."

Under-absorption, most likely. Fixed cost that no unit carried, reported as its own line rather than buried in a year-end adjustment.

"Our unit cost was worked out years ago."

At a volume you may no longer run. Recalculated as a curve it shows how exposed the business is to output falling.

"Only one person can close the production numbers."

A single point of failure in the process. Documented steps and scheduled consolidation make the close repeatable by anyone.

"The production workbook grinds on every entry."

Usually whole-column volatile functions recalculating the year. On proper tables each entry is immediate.

A quick check

Signs the Unit Cost Cannot Be Trusted

Nobody plans this work. It follows a quarter where output slipped and the result slipped much further. Earlier signals look like this:

  • One blended unit cost mixing variable and fixed
  • No volume assumption stated anywhere in the costing
  • Changeover is not measured or not recorded at all
  • Run lengths follow habit rather than a calculation
  • Absorption is adjusted at year end, not reported monthly
  • The cost curve has never been plotted across volumes
  • Stock holding cost is not in the batch decision
  • Nobody can say how exposed margin is to a volume drop

What the single figure costs

The expensive version is quoting a long-run cost on short-run work. The price was built at a volume the business no longer achieves, every job looks acceptable against it, and the shortfall only appears as an absorption adjustment months later.

The quieter cost is run length left to habit. Too many changeovers consume capacity that was never sold; too few tie up stock that has to be financed. Both are invisible until somebody prices the changeover.

What happens before a quote

We look at the production records, the cost ledger and the timesheets, and at whether changeover time is recorded anywhere. That single point usually decides how much of this is measurement and how much is rebuild.

Frequently the finding is that a variable-fixed split and a cost curve settle most of it, and that is the recommendation. Where a pricing decision genuinely belongs with you alone, you will be told so. The first conversation is unpaid either way.

Work delivered

Three Builds and the Results Recorded

Real projects for real organizations, each figure as reported by the client after the tool had bedded in.
Excel budgeting template with tiered access across thirty companies

66% better
accuracy

A budget tool across thirty businesses

At the outset
Thirty companies under one management group, each budgeted independently and merged by hand afterward, with several people needing different levels of access to a single file.
What we delivered
A template carrying layered permissions, VBA lifting each approved budget into a master sheet, payroll, tax and benefits adjustable at the front, and totals loading directly into the accounting system.
Afterward
Keying figures twice stopped altogether. Accuracy climbed 66%, the build cycle ran more than ten times quicker, and reforecasting mid-year became something they could do.
Automated report drawing on more than fifty sources

40 hours
a month back

Reporting that had always been manual

At the outset
Internal management reports and submissions to outside funding institutions were built by hand, with one update cycle capable of running to three days.
What we delivered
A program pulling more than fifty sources into one document in roughly five minutes, letting each source be inspected first and turning out drafts for comparison.
Afterward
A job that had filled a working day now finishes in minutes, returning forty person-hours or more every month from effort that produced nothing new.
Workbook rebuilt onto native Excel tables with pivot tables and slicers

9 minutes
to 30 seconds

A file that had become unworkable

At the outset
Finding one row among twelve hundred could take as much as nine minutes, the result of array formulas piled on each other and years of code added without review.
What we delivered
The data rehoused on native Excel tables, pivots and slicers taking over the search logic, and the surplus array formulas and VBA taken out rather than tolerated.
Afterward
Thirty seconds for the same row on the same machine. What had held it back was the arrangement, never the hardware.

Who we work with

Industries We Serve in Harrisonburg

The six areas JAAD Group covers, described as they appear where output is counted in units.
Manufacturing and Logistics icon

Manufacturing & Logistics

Supply chain analysis, production scheduling, vendor performance. Processors and packers whose unit cost moves with the length of the run.
Finance and Accounting icon

Finance and Accounting

Cash flow management, P&L tracking, budget analysis. Businesses whose price list carries an unstated volume assumption inside it.
Real Estate and Construction icon

Real Estate & Construction

Investment models, cost forecasting, expense tracking. Fabricators producing repeatable components alongside bespoke work.
Retail and E-commerce icon

Retail and E-commerce

Inventory monitoring, sales tracking, profit calculations. Sellers whose pick and pack cost per order depends on batch and volume.
Healthcare and Insurance icon

Healthcare & Insurance

Patient record systems, policy tracking, compliance reports. Labs and processors costing per sample across variable throughput.
Education and Training icon

Education & Training

Enrollment reports, course progress dashboards, grant tracking. Providers whose cost per learner falls sharply as a cohort fills.

If your industry relies on Excel for financial analysis, data tracking or reporting, we can optimize and automate your workflows to save time and improve performance.
How it runs

Working With an Excel Consultant in Harrisonburg

Five stages. The opening one is unpaid, and plenty of enquiries conclude there with guidance rather than a quotation.

  1. Say what you make and how the unit cost was worked out

    And at what volume. Sending production records and the cost ledger makes the call considerably sharper, though it is not required.

  2. We check the split and whether changeover is recorded

    What genuinely varies per unit, what is being absorbed, and whether setup time exists anywhere in the records.

  3. Scope and figure, documented

    Both settled before construction. The records have been read by then, so vagueness about either would be a decision rather than a necessity.

  4. Built in view

    Each working version arrives as it is finished rather than everything at the end, which is what makes an early change inexpensive.

  5. Handed over complete

    The workbooks, any code behind them, a written note of the split and the volume points used, and time with whoever will maintain it.

Jeff Mattus, Owner and President of JAAD Group Excel Consulting

Who does the work

Jeff Mattus

Owner & President, JAAD Group

JAAD Group is one person, Jeff Mattus, who put the practice together over more than twenty-five years of Excel and Office systems work and who arrived at the field through Computer Science rather than through a finance department. Where a single number is standing in for a relationship between two variables, that is the instinct that plots it.

The projects have reached into finance, healthcare, technology and property. The range is why an opening call usually ends in a diagnosis rather than a discovery phase: absorption behaves identically whether the unit is a case, a sample or a seat on a course.

Delivery is remote, so a Harrisonburg engagement runs exactly as a local one would. Whoever takes the first call prices the job and then builds it.

Organizations we have built for

Trusted With Business-Critical Spreadsheets
CAPTRUST
Trutina
Linmore LED
Gro-Well
McGregor Benefits
The Benefits Academy
Glen Acres HOA
Health Insurance Team
SSIS
OEC
SBA
Jesse Consulting

Why a specialist

Why Harrisonburg Businesses Use a Dedicated Excel Consultant

A single discipline

Excel, VBA and Office automation are the entire practice, which is why an opening read is usually accurate and the estimate close to the final number.

Built for the quote on Friday

A unit cost expressed as a curve lets you price the volume actually in front of you, rather than the volume the costing assumed years ago.

Reshape ahead of rebuild

Where the existing records can be extended rather than replaced, that is the advice, and it is the cheaper route by a wide margin.

Handed over documented

Written explanation, any code and training are part of delivery, so the curve keeps being refreshed after the build.

Numbers the clients reported

Each outcome quoted above came from the organization running the tool, and all three builds appear at length earlier.

Remote, so it starts at once

Everything happens over a shared screen, so a quote that has to go out this week gets attention today.

Questions

Frequently Asked Questions

What does Excel consulting in Harrisonburg usually involve?

Most often it is splitting production cost into what varies per unit and what is simply being absorbed, then expressing unit cost as a curve across several volumes.

After that it is pricing changeover as lost output, deriving economic batch size per product, and reporting under-absorption in the month it happens.

Why can you not just tell me the unit cost?

Because it is not a property of the unit. The same item costs materially more per unit at half the output, since the fixed cost it absorbs has not changed and fewer units carry it.

A single figure therefore hides a volume assumption. Expressed as a curve across the low, typical and full month, the figure becomes usable instead of comforting.

Our price did not change but margin fell. How?

Volume almost certainly did. Every price list has a volume assumption built into its costing, and output below that level means fixed cost went uncarried.

That is why nobody can point to a decision that caused it. The erosion came from the denominator, not from a price or a cost going up.

Why price changeover separately?

Because it is capacity rather than overhead. Setting up, cleaning down and running trial pieces consume productive time and produce nothing sellable.

So the real cost is the output lost rather than the labor spent. Measured per changeover and multiplied by frequency, it explains the busy month that produced very little.

How is economic batch size worked out?

By balancing two costs that move in opposite directions. Bigger batches spread changeover over more units and increase the stock being financed.

Smaller batches cut stock and multiply changeovers. There is a size minimizing the sum, it differs per product, and it is arithmetic once changeover and holding cost both exist.

What is under-absorption and why report it monthly?

It is fixed cost that no unit carried because output fell short of the volume the costing assumed. Reported as expected, actual and the gap, it has an obvious cause.

Left to a year-end adjustment it arrives as an unexplained variance long after anything could be done, which is why managers generally ask to see this line again.

What does an Excel consultant cost?

Scope decides it, which is why the records are examined before any figure is named and why that examination is free. A cost split with a volume curve is fixed-price.

In every case the deliverable and the price are agreed in writing before any building begins.

Do you work on site in Harrisonburg?

The work is delivered remotely by design rather than by limitation. Going through production and cost records together on a shared screen is identical at any distance.

It also means a quote that has to go out on Friday gets looked at on Tuesday, and no part of the invoice is travel.

The person who built our costing has left. Is it recoverable?

Usually. The costing gets read back to first principles, the split and the volume assumption reconstructed, and each fragile part repaired or replaced as honestly warranted.

What the work needs is time with whoever runs production now, because what they know about setup and run length matters as much as the file.

How long does a project take?

A cost split with a volume curve is often under a week. Adding changeover pricing, batch size modeling and monthly absorption reporting usually runs two weeks.

Whatever the size, that estimate is committed in writing before building starts rather than emerging as the work proceeds.

What do we keep at the end?

The workbooks, any macro source code, a written note of the variable-fixed split and the volume points used, and training for whoever will maintain it.

Nothing is locked to us and no subscription is needed to keep it running. Support afterward is available and entirely optional.

Are those six industries a limit?

No. They describe where most of the work has come from rather than what is accepted, and what decides scope is the nature of the problem rather than the sector.

A case of product, a processed sample and a filled seat on a course all absorb fixed cost in exactly the same way.

Also serving

Excel Consulting Across Virginia

Everything is delivered over a shared screen, so your address has no bearing on the result. Other Virginia cities with their own pages:

By service: Excel consulting for the cost split, financial modeling for batch size, Excel reporting for absorption, Excel automation for the production close, and VBA and macro development or Excel expert help for the rest.

Harrisonburg is the hub here — schematic, not to scale

Send Us the Workbook

Tell us what you make and how the unit cost was worked out, or attach production records and the cost ledger. You get a flat read on where your real unit cost sits, with nothing committed.

949-464-7489

JAAD Group Excel Consulting · 2937 Hawksdale Dr, Las Vegas, NV 89134
Excel consulting services in Harrisonburg, VA and across Virginia, delivered remotely